

Beyond the Noise: what AI means for trusted adviser relationships
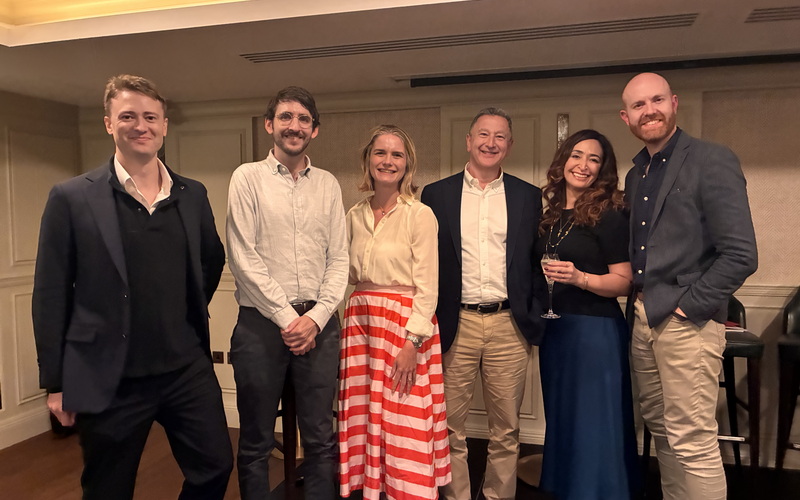
AI will not replace the trusted adviser, but it is already changing what clients expect that adviser to be. That was the message from our panel event last week, speaking to a packed room of lawyers, accountants, financial planners and wealth advisers at Home House Studio in central London.
Opening the event with a quick show of hands, it was clear that nearly all our guests already use AI in some form. The question on everyone’s minds was how AI might fundamentally change the relationship between client and adviser in the long term – but crucially also – how AI can be used today to improve the client experience.
James Addison, BKL’s COO who drives the company’s AI strategy, hosted the evening. We opened with Paddy Stobbs, co-founder and CEO of StackFix, followed by a panel with:
- Alex Hern, AI writer for The Economist
- Simon Levine, strategy consultant and former managing partner of DLA Piper
- Naz Keceli, CEO of AI consultancy Khiliad Legal
- Harriet Griffin, COO of wealth manager Quanta Group
Why your business should take notice
Paddy’s business helps other firms integrate AI into their systems, and he sees that AI’s biggest impact on advisers may be the shifting expectations of clients.
Where a client once arrived with an open question, they may now present work half-done, and ask their adviser to check it, strengthen it and sign it off. Scoping and pricing that kind of work will be harder than it looks.
He also expects clients to want advisers who keep a constant eye on their affairs and are available well beyond office hours.
The people building AI mean what they say
Alex had just returned from six days among the AI labs of San Francisco. His message was quietly sobering: the people building these systems are sincere about the impact they think AI will have on business and society in the longer term.
Many feel uneasy about the speed of progress but feel unable to slow down while the race with China continues. His advice was to plan on the assumption that they will achieve what they say they are aiming for.
However the macro picture plays out for AI, it seems clear that every adviser now needs a clear answer to a simple question: why does a client come to me?
Trust is emotional, and that changes the maths
Simon offered one answer: people are not purely rational buyers of advice. Most of us would not want a serious diagnosis from a machine alone. Clients will happily pay for that reassurance, but only at a price that reflects what the professional is now doing.
That puts the billable hour under more pressure. Simon remembered joining the City in 1988, before timesheets ruled working life, when firms charged for the value of their work. In his view, AI will bring back a return of the debate about whether the professions continue pricing by time.
Naz is already seeing the impact on the law firms she advises. She described a client who runs every piece of legal advice through AI to double-check it, and clients are asking questions about the impact of AI on their invoice. Yet AI is also making advice affordable for smaller businesses that previously went without, and increasing the addressable market for our services.
Less admin, better conversations
At Quanta Group, Harriet explained that AI now transcribes client meetings and takes on much of the record keeping that regulation demands. The result is not fewer advisers but better conversations, because advisers can listen rather than tick boxes.
When things go wrong, a financial adviser is often among the first people a client calls. With only a small minority of the UK population receiving financial advice, AI could help many more people get the support they need.
What we do know
…Is that the firms that thrive will be those that use AI to deepen client relationships, not simply to do the same work more cheaply. As James Addison said:
“The best advice has always been built on people and trust, and that won’t change. What AI gives us is the chance to spend less time on routine tasks and more time understanding what our clients need. The question for every adviser isn’t whether to use AI, but how to use it to make those relationships stronger.”
The advantage lies in building that deep knowledge of your clients, their history and the decisions they have made with you. AI makes it possible to put that knowledge to work continuously, spotting a cashflow squeeze or contract risk rather than waiting for the next scheduled review.
It also lowers the barrier to doing things differently. Alex borrowed a Silicon Valley slogan, “You can just do things”, to describe how one person can now build the dashboard, tool or workflow that once needed a team. Naz described a criminal law firm of more than 40 people redesigning its entire workflow around AI: not to cut staff, but because it simply cannot hire enough people.
Human oversight has to mean something, though. Alex pointed to research on self-driving cars that describes a “moral crumple zone”, where the human in the loop is there mainly to absorb the blame. If your review of AI output becomes a rubber stamp, it protects no one. As Simon made clear in response to a question from the floor, the individual professional remains liable and therefore crucial.
What happens next
Change may be slower than the hype suggests, but looking 18 months ahead, the direction is clear.
Simon expects the firms that embrace AI to pull ahead of those in denial. Harriet hopes it will open up advice to far more people, and Naz urged everyone to experiment now, while the tools are relatively affordable and accessible.
How BKL can help
We work with professional services firms and their clients to make sense of change and turn it into opportunity.
Whether you are rethinking how you price your services, exploring where AI could save time, or considering what new advisory offerings might look like, we can help you make proportionate, commercially grounded decisions.
For a chat about what AI could mean for your business, get in touch using the form below.
Contact us
Frequently asked questions: what AI means for trusted adviser relationships
Will AI replace accountants, lawyers, financial advisers and other trusted advisers?
No. AI is more likely to change the role of professional advisers than replace them entirely. While AI can automate research, analysis, drafting and administrative tasks, clients still value judgement, accountability, context and reassurance when making important decisions. Trusted advisers bring industry knowledge, commercial understanding and an appreciation of a client’s wider circumstances that AI tools cannot fully replicate. For many businesses, AI will become part of the advisory process, but human expertise will remain central to high-value decision-making.
How is AI changing what clients expect from professional advisers?
AI is raising expectations around speed, accessibility and value. Increasingly, clients may arrive having already used AI tools to research a problem, draft a document or analyse data. Rather than starting from scratch, they may want advisers to review, validate and strengthen AI-generated work. This shifts the focus from producing routine outputs to providing strategic guidance, quality assurance and accountability. Firms that adapt to these changing expectations are likely to be better placed to strengthen client relationships.
If AI does part of the work, why would I still pay for professional advice?
Professional advice is not simply about producing an answer. It is about ensuring the answer is accurate, relevant, compliant and appropriate for your specific circumstances. AI tools can generate content and recommendations, but they can also make mistakes, misinterpret facts or overlook risks. Businesses often require expert review, professional judgement and, in regulated areas, a qualified adviser who is willing to stand behind the advice provided.
Who is responsible if AI-generated advice turns out to be wrong?
Responsibility does not automatically transfer to AI. Where a professional adviser reviews and signs off advice, they generally remain accountable for the quality and appropriateness of that advice. Businesses should therefore be cautious about treating AI outputs as verified simply because they were generated confidently. Effective oversight requires meaningful review and challenge, not just approving AI-generated work without scrutiny.
Should professional services firms rethink how they price their services in the AI era?
In many cases, yes. As AI reduces the time required for certain tasks, clients may increasingly question pricing models based primarily on hours worked. This is prompting discussion across professional services about value-based pricing, fixed-fee arrangements and outcome-focused billing. While there is no single approach that suits every firm, advisers may need to demonstrate value through insight, strategic thinking and results rather than time spent completing routine work.
Can AI help smaller businesses access professional advice?
Yes. AI has the potential to make aspects of professional support more affordable and accessible for smaller businesses that may previously have been priced out of certain services. By automating routine processes, advisers can often deliver support more efficiently, allowing businesses to access expertise that might otherwise have been unavailable. However, important decisions should still be reviewed with appropriate professional input, particularly where legal, tax, financial or regulatory risks are involved.
What are the biggest risks of relying too heavily on AI for business decisions?
The main risks include inaccurate information, incomplete analysis, regulatory compliance issues, confidentiality concerns and overconfidence in AI-generated outputs. AI systems can produce persuasive answers that appear correct but contain errors or unsupported assumptions. Businesses should establish governance processes, maintain human oversight and ensure important financial, legal, tax and strategic decisions are reviewed by appropriately qualified professionals before action is taken.
How can firms use AI without weakening client relationships?
The most effective use of AI is often to support, rather than replace, human interaction. Many firms are using AI to automate notetaking, record keeping, research and administrative processes, freeing professionals to spend more time with clients. This can improve responsiveness, deepen conversations and create more opportunities for proactive advice. Used thoughtfully, AI can strengthen the adviser-client relationship by allowing advisers to focus on the areas where human insight creates the greatest value.
What practical steps should businesses take before implementing AI tools?
Businesses should start by identifying specific problems they want AI to solve rather than adopting tools for their own sake. It is important to assess data security, confidentiality obligations, regulatory requirements and governance processes before deployment. Organisations should also establish clear review procedures, train staff appropriately and define where human approval is required. A structured approach helps ensure AI delivers genuine business value while managing operational and compliance risks.
How can professional services firms prepare for the future of AI?
Firms should focus on developing the capabilities that clients cannot easily obtain from a generic AI tool. This includes deeper sector expertise, stronger client relationships, commercial judgement and the ability to apply knowledge in a practical context. At the same time, firms should actively experiment with AI, review operating models and consider how technology can enhance efficiency and service delivery. Those that combine technology with trusted human advice are likely to be best positioned as client expectations continue to evolve.